In October, we assumed Shanxi’s production cuts would largely hold through Lunar New Year. A month later, mines are already restarting. That’s taken a bit of the steam out of our winter forecast, but it hasn’t changed the central call in our Met Coal Short-Term Outlook. We still think the SGX curve is too bearish on Q1.
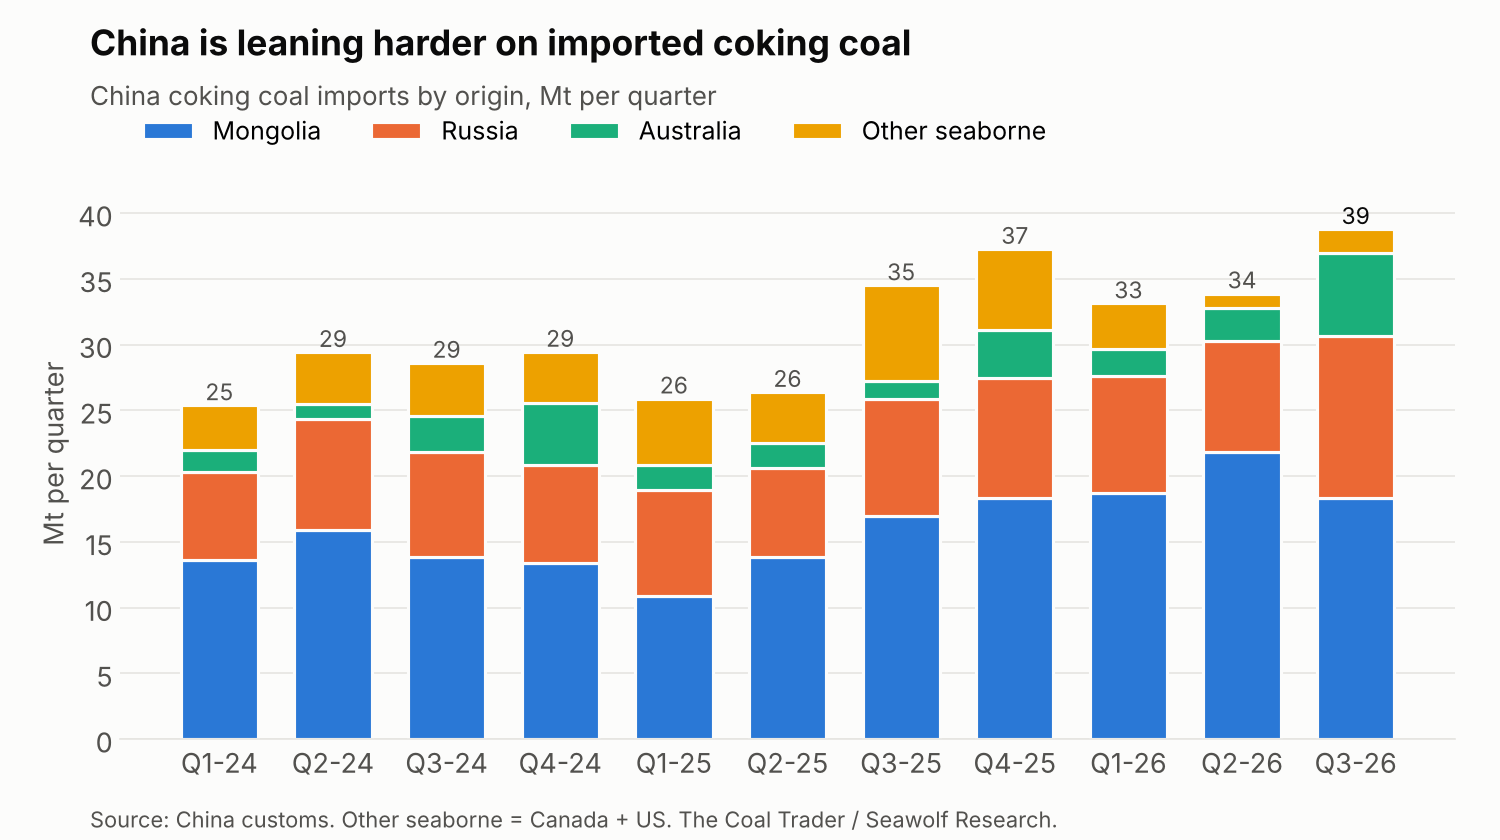
Australian premium low-vol hard coking coal (PLV) averaged $267/t in October, down from $278/t in September. Chinese domestic coking coal prices have eased as buyers anticipate more supply from Shanxi, taking some of September’s premium out of seaborne spot. But getting mines back online isn’t the same as getting output back to normal. We still expect Chinese mills to lean more heavily on seaborne coal this winter
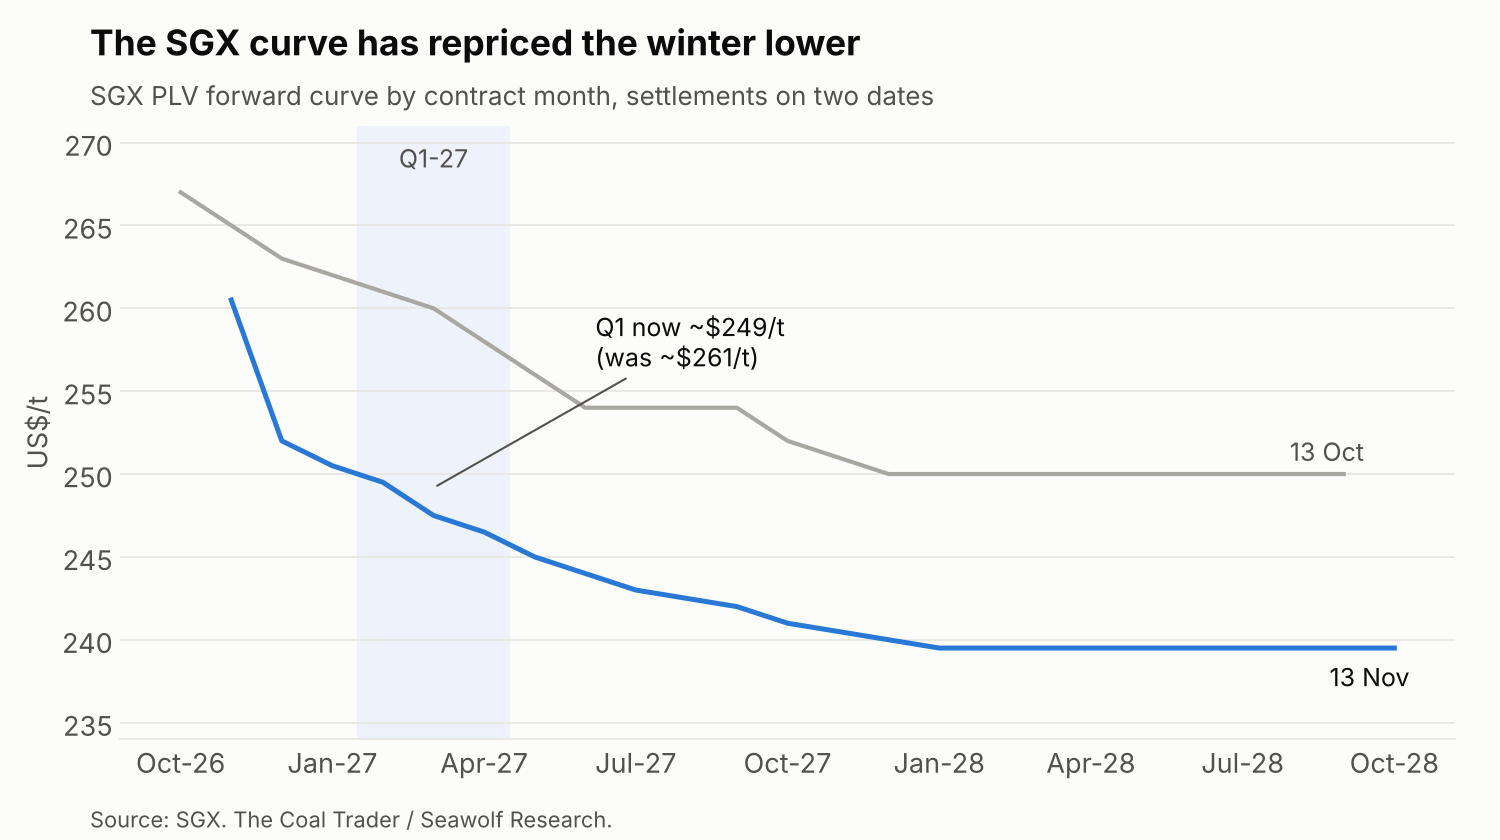
The SGX curve has moved lower too. As of November 13, Q1 was trading around $249/t, still below where we see the quarter averaging.
What changed since October
Our Q4 view is essentially unchanged, but the path into winter is flatter. We no longer expect prices to turn up in late December, and we’ve cut our Q1 PLV forecast by about $5/t on a softer January and an earlier fade in March. We still expect some lift as mills buy ahead of Lunar New Year. A faster return to normal output in Shanxi remains the biggest downside risk.
We already expected the market to loosen from spring as Mongolia’s new rail link brings more coal into China. What stands out in November is India’s ability to support prices even as that happens. Indian mills are using less coking coal per tonne of steel, which helps explain why their imports have fallen this year despite higher steel output. But margins are healthy and port stocks are a little below normal. Mills have room to pay up when they need tonnes, even if they’re using coal more efficiently.
Read the full November outlook
The second issue is live. It includes our 24-month price forecasts by grade, the full China balance, supply and demand by country, and scenarios that show what a faster Shanxi recovery would mean for prices. The report comes with an Excel workbook.
Already a website Premium subscriber? Read the November issue here. The Outlook is included with Premium through December 31, 2026, including the December issue.
Reading on Substack, free or paid? A TCT Website Premium subscription is $699/year and includes paid Substack access, our coal dashboards, and company research. Join before year-end to get the Outlook while it’s still included.
On January 1, 2027, the Outlook moves to our $15,000/year Institutional tier, and Premium access to the report ends.
Subscribe to TCT Website Premium →
-MW