To be honest, not much has really changed since the last time we encountered HCC 2.41%↑ which is rallying today with the broader market, and alongside PLV met coal prices stabilizing in the mid-$180’s. So really all we’re looking to do here is calculate the subtle changes in production, prices, and costs.
Blue Creek remains on track to be a fully operational battle station by 2027. But a declining 2024 market and disappointing recent realizations for HVA production have held the stock down, while the small cap/high short interest factor rally into restocking season over the past month has rekindled hopes of returning to the $70’s.
In this market largely driven more by vibes than fundamentals, we must respect the vibe.
But in the meantime let’s peek under the hood down in Alabama and see how things are going…
This Substack is reader-supported. To receive new posts and support my work, consider becoming a free or paid subscriber.
Production
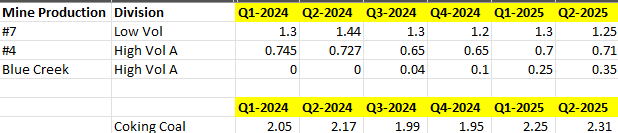
MSHA production reports show the company produced 2.31 million short tons (st) of coal in Q2, with Blue Creek’s ramp up from 250k to 350kst offset slightly by a 50kst decline in output at the company’s low-volatile No 7 Mine.
Source: MSHA
Prices
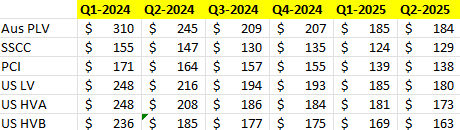
On the pricing side, PLV mostly held steady in Q2, but US indices for Low-volatile and High-Volatile A coal – Warrior’s key products – fell by 2.5% and 4.5%, respectively. The latter decline is likely due in some part to the lower realizations that Warrior (and to be fair, Peabody too) has received for their Blue Creek development tons.
Source: Argus, Seawolf Research
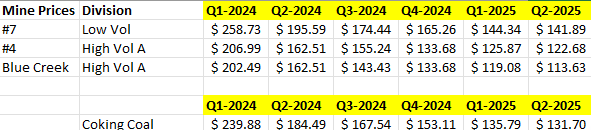
As such, we suspect realized prices will once again decline, this time by about 3% from $135.79/st down into the low $130’s.
Source: Seawolf Research
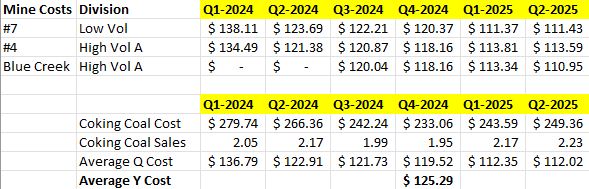
We have once again held last quarter’s cost readjustment over, giving a slight added benefit to Blue Creek due to improved production, as well as lower price-related costs.
Source: Seawolf Research
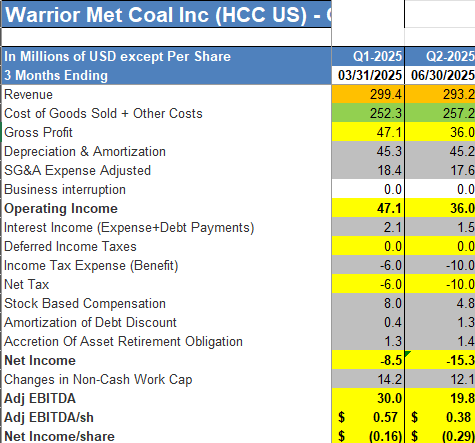
We have almost nailed revenue the past two quarters, so again, no changes to methodology for us there. But given that more tons were produced at similar costs, we expect total cost of sales to increase slightly from $252M to $257M this quarter. And as such, we expect to see a slightly bigger loss, going from -$0.16 to $-0.29 per share.
Source: Seawolf Research
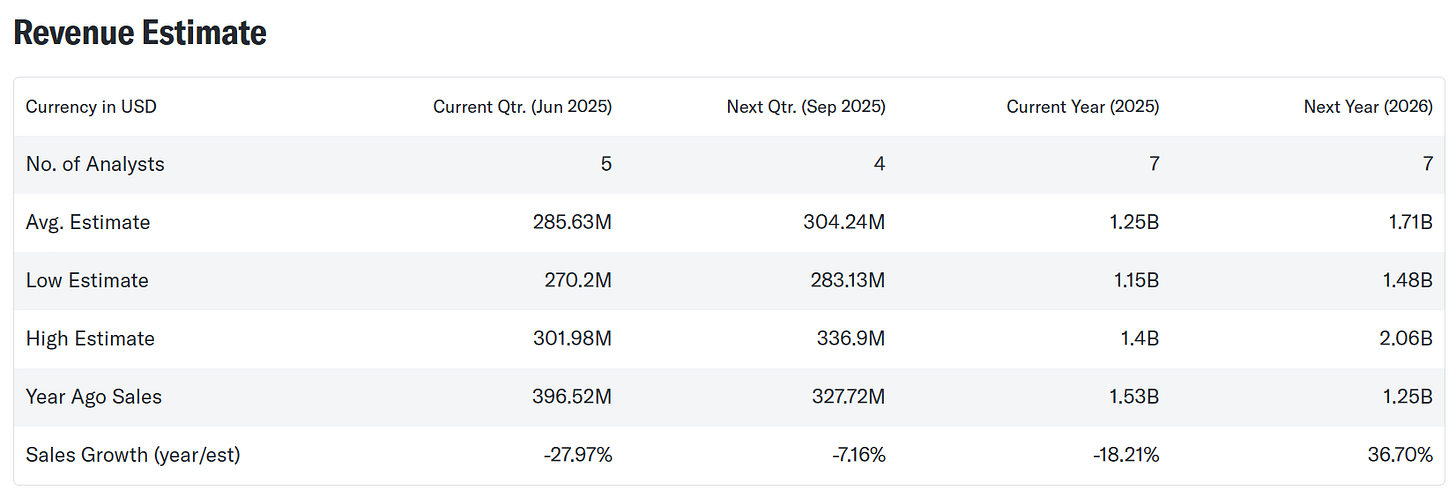
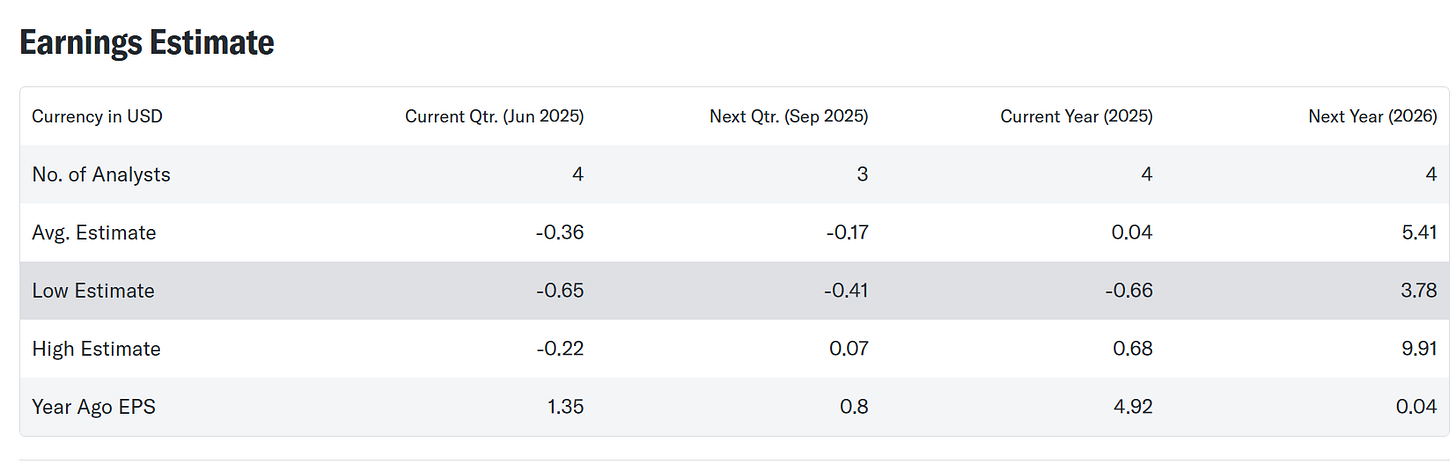
And that puts us right smack in the middle of other analyst estimates for the quarter.
Source: Yahoo! Finance
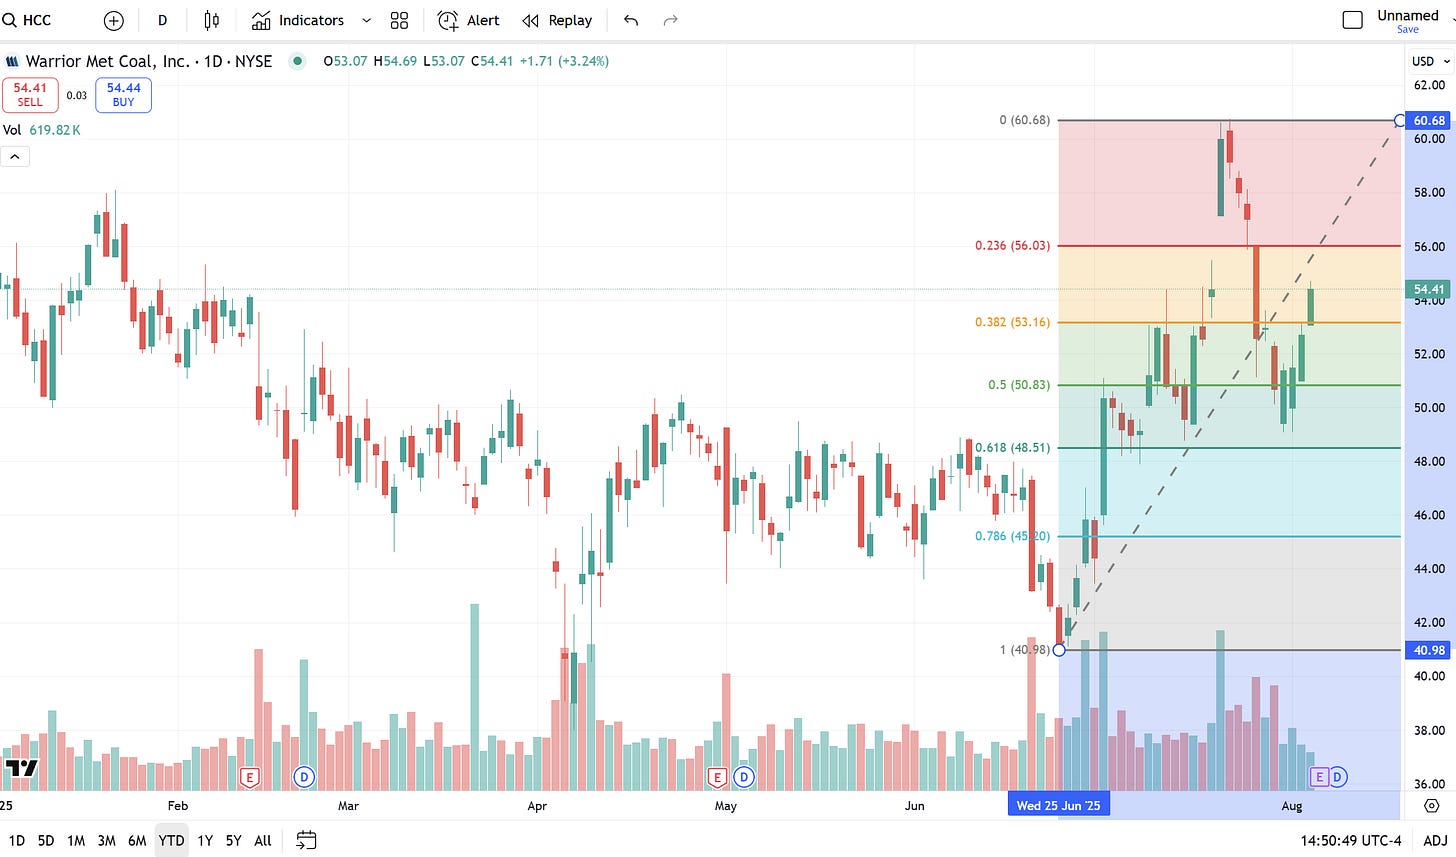
Using the Fibonacci Retracement of the stocks recent 50% (!!!) run, we can see potentially testing resistance levels at $56 and $60 per share on a beat. While on a miss the $50-51/share level would come into play.
Source: Tradingview
Last quarter, we said “a miss could send the stock back down into the low $40’s, where we would be slightly more aggressive buyers than we have been over the past few months.” Had we all followed that advice (I got out too soon, as per usual) this past month would have been an absolute banger.
This time around, it would have to be a BIG miss to send us back down into the low $40’s, so I’d target that $50-51 level instead for a new entry.
But as I’ve said many times in these previews, these are pretty small losses. And when you’re right on the cusp of profit, even small adjustments can make large relative swings in potential earnings outcomes.
So for me, it’s the same story as last time…hoping for disappointment so I can pick up shares on the cheap.
Which given my track record trading around median levels, it probably means Walt and Dale defy my expectations and send this stock to Saturn.
-MW